Start with the purpose of the money
An emergency reserve, a bill due next year and a retirement goal are different decisions. Write the amount, deadline and acceptable shortfall for each before comparing products. This India-focused article is general financial education, not a crash forecast, current rate table or personalized allocation. An alarming headline is not enough evidence to move all savings into one product.
Inflation changes purchasing power
The exact inflation-adjusted return is (1 + nominal return) / (1 + inflation) − 1. In a hypothetical year with a 7% nominal return and 5% inflation, the real return is about 1.90% before tax. If an illustrative effective tax of 20% applied to all interest, the nominal return would be 5.6% and the real return about 0.57%. These are teaching assumptions, not current rates or a statement of your tax treatment. Compare after-tax proceeds and actual charges for your circumstances.
Savings accounts and FDs solve different access needs
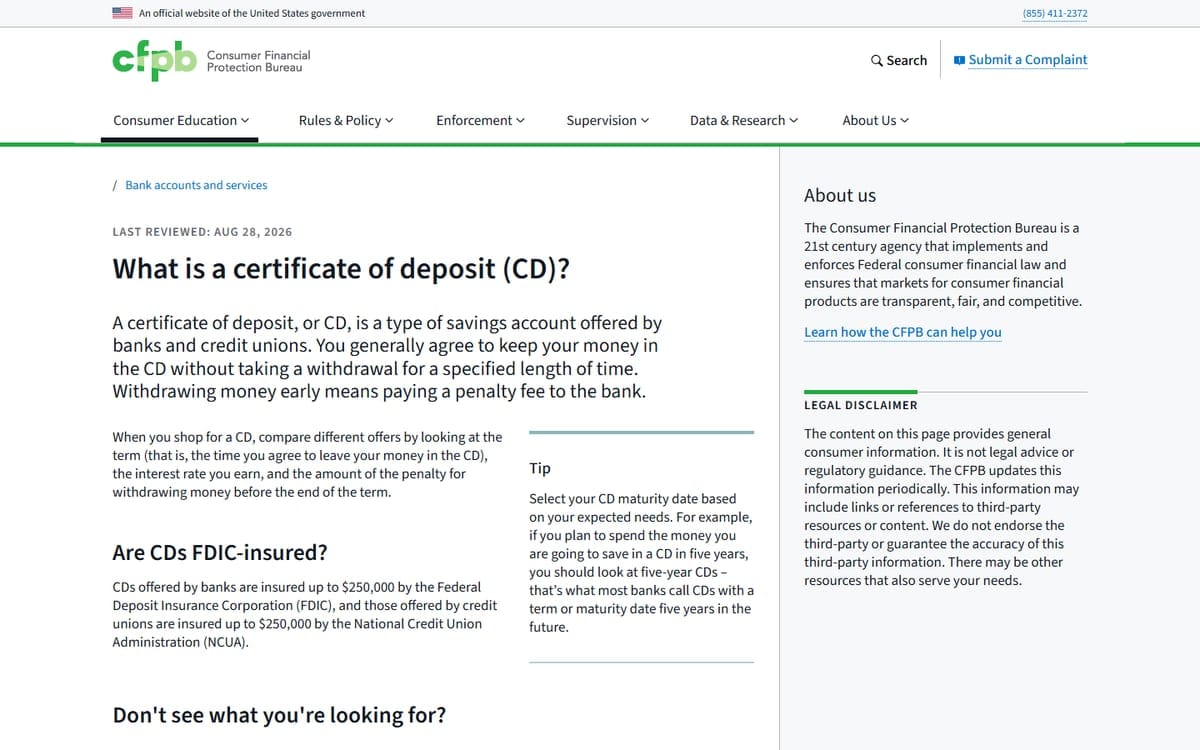
Compare a bank's current product terms, maturity date, premature withdrawal rules and renewal instructions. A quoted annual rate alone does not tell you whether money will be accessible when a bill arrives. Keep written records of maturity instructions and nominees where applicable. Do not assume a corporate deposit has the same protection as an insured bank deposit.
| Question | Savings account | Bank fixed deposit |
|---|---|---|
| Access | Check withdrawal and balance rules | Check maturity and early-exit terms |
| Rate risk | Rate may change | Check contracted rate and reinvestment at maturity |
| Net proceeds | Include tax and fees | Include tax and any early-exit penalty |
| Protection | Confirm insured bank and capacity | Combine eligible balances at the same bank |
DICGC cover is not per FD
DICGC covers eligible deposits up to ₹5 lakh per depositor per bank in the same right and capacity, including principal and interest. Eligible savings and FD balances at the same bank are aggregated. For example, ₹4.7 lakh principal plus ₹50,000 interest totals ₹5.2 lakh, so do not assume all of it falls within the ceiling. The guide excludes NBFC deposits, mutual funds, stocks, bonds and ETFs. Check eligibility and the applicable account capacity directly.
A market fall is not a reliable timing signal
Investor.gov describes asset allocation in relation to time horizon and risk tolerance and explains that diversification does not guarantee against loss. That framework helps distinguish money needed soon from money intended for a longer horizon. A stock-market decline can continue; waiting for an exact bottom can also fail. Before reacting, check whether your goal, debt obligations or ability to bear a loss has actually changed. This article does not recommend a stock, fund or trade.
Gold and silver can fall too
The CFTC warns that precious metals are not risk-free and highlights price volatility and fraud risk. Physical metals also involve dealer spreads, storage, purity and selling costs. A fund adds its own expense and structure considerations. A belief that metals protect against inflation is not a guarantee over your particular holding period. Compare the final buy-and-sell costs, not just a displayed spot price, and avoid promises of assured returns.
A simple decision checklist
List upcoming cash needs separately from long-term goals. Gather actual account and product terms. Calculate an after-tax example using assumptions you understand. Check the insured bank and aggregate balances. Consider whether any decision concentrates risk instead of reducing it. If the consequences are substantial or the tax treatment is unclear, seek advice from an appropriately qualified professional rather than relying on a general article.
- Keep required near-term spending visible.
- Check deposit protection rather than assuming it.
- Record fees, withdrawal restrictions and tax assumptions.
- Avoid borrowed-money bets on a crash or metals rally.
Frequently asked questions
Does every FD receive separate ₹5 lakh insurance?
No. DICGC aggregates eligible deposits per depositor per bank in the same right and capacity, including principal and interest.
Can a positive FD return still lose purchasing power?
Yes. Inflation and applicable taxes or charges can reduce the purchasing power of the proceeds.
Are gold and silver guaranteed protection during a crash?
No. Metals prices can fall and ownership involves costs and risks.
Is this a prediction of a stock-market crash?
No. It is an educational comparison of risks, liquidity and purchasing power, without a market-timing forecast.
Sources & further reading
Primary sources checked Oct 25, 2026. Vendor statements are attributed; editorial advice is our own.
- 1
- 2
- 3
Help us keep this useful. Report a factual correction →